With the power of the internet, anyone can now publish financial guidance, polished writing, confident claims, and clean design, and even act as a financial advisor without any qualifications.
This has become a major problem for readers seeking useful, trustworthy advice. They have no way to distinguish right information from misinformation.
So, it’s now very important to know how to identify the difference and find the right information that fits your needs. Read this blog to learn What Makes an Online Financial Resource Worth Trusting.
Four practical checks reveal more than tone or presentation ever will:
A resource that fails three of these four checks is not worth further attention, however convincing its writing appears.
Choose one verifiable claim and follow it back to its source is the fastest way to grade a financial resource. If a publisher handles an easily checked figure carelessly, there is little reason to accept its harder-to-test claims without further investigation.
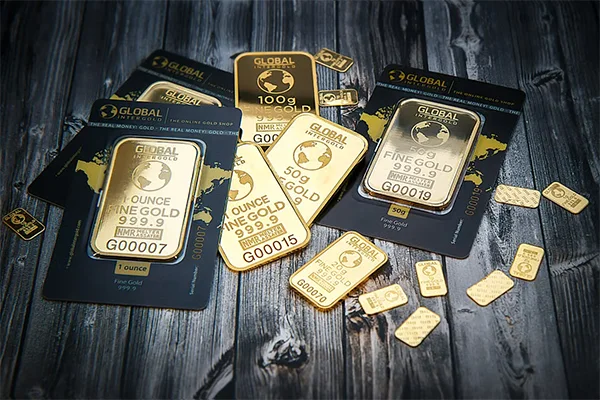
Hard assets provide a useful accuracy test because their underlying market prices are publicly visible. Suppose a product page describes a 1oz gold bar as a .9999 fine ingot for new investors. You can audit that description by checking the stated purity and weight, then comparing the quoted price with that day’s spot price and the seller’s disclosed premium.
That comparison separates the metal’s benchmark value from dealer costs and margins. It is selling rather than reporting. If a page presents a precious-metals price without identifying the spot price, premium, or quote date, it fails.
Cross-verification of information should happen before the figure influences a financial decision. AI chat responses and figures shared through screenshots often fail the same test. They may provide a plausible number without a dated primary source, so they work better as unverified drafts than final answers.
Evidence and data to support claims provide Reliable pages, but a hyperlink alone is not enough. Rather than another article repeating the same figure. The link should lead to the original filing, report, or dataset. A reference to economic research, for example, should identify the dataset from the Federal Reserve Bank of Philadelphia and the period covered or relevant publication.
The date of publication matters as much as the source. A statistic without a year can circulate long after its context has changed, while a clearly dated figure lets you judge whether it remains relevant. Recycled numbers without a reporting period usually indicate that nobody has properly reviewed the page since its publication.
A byline is a claim, not a qualification. Checking the person or firm behind financial content takes only a short search through free public records, and it provides more useful information than a polished biography.
Start at Investor.gov and search to enter the person’s or firm’s name using its investment-professional. Then search the Securities and Exchange Commission’s adviser records, select the matching firm, and open its registration documents. Registration can fall under federal or, depending on the firm’s size, state oversight, so check the relevant state securities regulator as well.
Review disciplinary disclosures and employment history, including unexplained gaps or frequent moves between firms. Do not stop when a record appears.
Confirm a certified financial planner (CFP) designation through the certifying board’s public verification tool rather than trusting a profile logo. When fee-only status matters, NAPFA (National Association of Personal Financial Advisors) listings provide another record to compare with the author’s claims. Similar source checks help when evaluating expert-backed reviews, where the reviewer’s expertise should match the subject being assessed.
They do not turn every TikTok clip or YouTube video into personal advice, but Verified credentials establish identity and professional history. A licensed creator publishing general content does not owe each viewer that same duty of care. A fiduciary standard applies within a particular client relationship.
Accordingly, state securities regulators advise checking credentials before acting on social posts, researching the investment, reviewing conflicts, and consulting multiple reliable sources.
Anonymous or pseudonymous writers are not automatically wrong. However, without a verifiable identity or professional history, every meaningful claim must stand on independently checkable evidence.
The useful question is not whether money is involved, but whether the publisher explains who provides it and whether honest coverage could work against that payer’s interests. Every financial resource is funded somehow.
Directly beneath the headline, or inside a collapsed footer. Disclosure language often appears above the article in a grey box. If it does not identify the types of partners involved, a statement that “we may be compensated” offers limited transparency about funding. A named partner list makes the potential conflict of interest easier to assess.
What disclosure language leaves out can be revealed by Page design. A comparison table in which every entry links to a seller, while inconvenient or poorly rated choices never appear, is an affiliate placement presented as editorial selection. The publisher still reports unflattering findings. Sponsored content is not automatically unreliable when it is labelled, and t
Sensational headlines and get-rich-quick promises are also monetisation signals, especially when they lead directly to a paid course, referral link, or contact form. A blunt warning that names a specific risk differs from fear-mongering designed to force a quick decision. The same distinction matters when recognizing online scams: pressure and hidden incentives reveal more than an exciting claim.
A calculator only needs inputs required for its calculation. A retirement projection might need age, savings, and assumptions, but it does not need a phone number to produce arithmetic. ZIP-code matching, mandatory email fields, and results withheld until submission indicate lead generation rather than calculation.
HTTPS protects the connection, but it does not explain what happens to submitted financial information. If it does not say who receives the information, declining the form is the safer decision. The privacy policy should state whether data is sold or shared and identify the categories of recipients.
Public resources associated with the Consumer Financial Protection Bureau and MyMoney. Because their educational material is not built around completing a commercial sale, government sites provide a useful contrast. It makes the funding model easier to understand, but that does not make every government page current,
Authors change, funding arrangements shift, old figures remain online, and editorial standards can weaken without an obvious change in design.No financial website earns permanent trust.
Rather than once to an entire website, the checks used here are inexpensive enough to apply to each page that matters. A general budgeting explanation needs less scrutiny than guidance informing a retirement transfer or disclosure of sensitive financial information. Or investment purchase. Trust should rise only as the evidence becomes stronger, and scrutiny should increase with the size of the decision.
Trustworthy sources are verifiable, current, transparent about incentives, and appropriate to your legal and financial context.
Evaluate Credentials, Cross-Check Information, Be Cautious of Promises, Understand Conflicts of Interest, and Seek Professional Guidance.
Overabundance of Information, Lack of Regulation, Confirmation Bias, and Viral Misinformation.
Check Credentials and Expertise, look for Transparency, cross-verify, and evaluate the Tone and Promises.