Alternative credit scoring services hold value because most lending portfolios contain applicants that a bureau file defines badly or does not describe at all.
The eight providers in this article take genuinely different routes to the same results. Some deliver a score, while some deliver models; some deliver access to a data source the lender could never assemble solely.
Selecting the best depends on where the signals enter the credit decisioning process, how quickly it can be tested against historical outcomes, and whether the vendor operates in the market the portfolio actually serves.
The strongest options from this guide, for teams that want a shortlist before reading the full breakdown.
Standout capability: privacy-first behavioural scorecards built from device and web metadata, with no personal data collected.
Best for: Lenders who require predictive lift on each applicant, particularly thin-file and no-file across many countries.
Standout capability: Telco-driven risk models with broader reach across Southeast Asian mobile subscriber bases.
Best for: lenders in markets where mobile network data offers the deepest coverage.
Standout capability: Machine learning underwriting built on the lender’s existing application and performance records.
Best for: US institutions that already hold years of clean loan performance history.
Rankings are based on published product documentation, developer materials, partner listings, market coverage disclosures, and buyer commentary. Use these 4 checks to shape the final order properly.
Scores legitimately combine three dimensions. Features carry 40 percent, covering depth of signal, model support, and integration options. Convenient usage holds 30 percent, and that covers deployment efforts, documentation quality, and time to first score. Meanwhile, value carries 30 percent, including coverage breadth relative to cost of adoption.
| # | Provider | Data type | Category | Score | Visit |
| 01 | Credolab | Device plus web behavioural metadata | Specialist platform | 9.2/10 | Visit |
| 02 | TrustingSocial | Telco data with AI scoring | Regional specialist | 8.6/10 | Visit |
| 03 | Zest AI | ML on lender’s own data | Enterprise vendor | 8.3/10 | Visit |
| 04 | Motiv8AI | SDK data plus behavioural psychology | Specialist platform | 8.0/10 | Visit |
| 05 | RiskSeal | Digital footprint enrichment | Specialist platform | 7.7/10 | Visit |
| 06 | FinScore | Telco scoring | Regional specialist | 7.4/10 | Visit |
| 07 | Lenddo EFL | Device, behavioural, psychometric | Specialist platform | 7.1/10 | Visit |
| 08 | Findo | Mobile and social signals | Regional specialist | 6.8/10 | Visit |
Builds behavioural scorecards from anonymised smartphone and web metadata collected through an embedded SDK, with no personal data leaving the device.
Best for: lenders that need predictive lift on every applicant, especially thin-file and no-file, across several countries.
Credolab occupies an unusual position in this category because it never touches the underlying content of a device. The SDK reads metadata: how many calendar entries exist, how storage is organised, how a form is filled, how a session behaves. That raw material becomes 11+ million behavioural features, and the machine learning engine converts those features into a score that returns in real time during the application flow.
The privacy design holds commercial weight because, with no contacts, messages, photos, or personal identifiers, risk teams face a lighter data protection review than device-scraping alternatives generally trigger. Scores arrive as a variable that can lie alongside a bureau score instead of replacing it. That suits lenders running champion-challenger tests before committing to a policy change.
The score is available through the FICO Marketplace, and coverage extends across the United States, Southeast Asia, Latin America, Africa, the Middle East, and parts of Europe. Model development runs on the lender’s own results data, so the scorecard reflects the portfolio it will govern.
Standout capability: Metadata-only behavioral scoring that produces a real-time risk score without gathering sensitive information.
Applies AI and machine learning to mobile network operator data to score borrowers with limited formal credit history.
Best for: Lenders in markets where mobile network data provides the deepest coverage.
TrustingSocial operates from a data source most providers cannot reach independently. Mobile operators hold years of recharge patterns, tenure records, mobility footprints, and payment regularity. This correlates with repayment behaviour in markets where formal banking penetration remains low. The firm packages that signal into risk scores and fraud checks.
Regional depth is the real asset. Coverage across Vietnam, Indonesia, the Philippines, and India rests on direct operator relationships, so match rates in those markets tend to be high. The tradeoff sits in geography: a portfolio spread across three continents will find coverage uneven, since any operator-dependent model inherits the reach of the partnerships behind it.
Standout capability: operator-grade telco risk scoring in markets with thin bureau coverage.
Offers machine learning underwriting models built on a lender’s own application and loan performance data, with documentation designed for US regulatory review.
Best for: Businesses that already hold years of clean loan performance history.
Zest AI handles the lender’s data as the alternative information. Instead of importing an outside signal, it rebuilds the scorecard using machine learning across variables the institution already gathers, then generates the adverse action reasoning and fair lending documentation that US supervisors expect. Credit unions and banks make up much of the client base.
The approach suits organisations with mature data. A lender holding a decade of application records, bureau pulls, and charge-off outcomes has enough raw material for a model that outperforms a legacy scorecard without any new vendor feed. What it will not solve is a coverage gap, since an applicant absent from both the lender’s files and the bureau leaves the model nothing new to read.
Standout capability: machine learning scorecards with fair lending documentation prepared for US examination.
Integrates SDK-collected smartphone data with behavioral psychology to interpret how emotional and habitual patterns relate to borrowing decisions.
Best for: Lenders invested in behavioral segmentation with a conventional risk score.
Motiv8AI gathers smartphone signals through an SDK, which places it in identical technical territory to other device-based vendors. The interpretive layer varies: rather than treating device metadata entirely as raw material for feature engineering, the company frames its analysis through behavioral psychology, which examines how patterns in phone usage relate to and contribute to money and repayment discipline.
That framing appeals to teams working on collections strategy, engagement design, or product fit rather than approval decisions alone. A psychological read on a borrower segment can inform how repayment reminders are worded or when they are sent, which is a different problem from ranking applicants by default probability.
Standout capability: behavioural psychology interpretation layered over smartphone SDK signals.
Enhances applications with digital footprint data drawn from online account and email presence checks.
Best for: Fraud screening and light applicant enrichment early in the funnel.
RiskSeal develops an image of an applicant from their internet presence. An email address or phone number is verified against a set of customers to watch where accounts exist, how long they have been active, and what that pattern shows about legitimacy. The result comes through an API and slots easily into an existing decision flow.
Depth is the limit. The published signal set covers around 400 data points, which is modest next to platforms generating 11+ million behavioural features. That size supports a useful supplementary check, though it rarely carries enough weight to serve as a primary risk score for thin-file lending.
Standout capability: fast API-based digital footprint enrichment with no client-side integration.
Offers telco-based credit scoring for the Philippine market through mobile network operator data.
Best for: Philippine lenders working for borrowers with no bureau record.
FinScore does one thing with actual focus. It produces a telco credit score for a market where a large share of adults hold no formal credit file, working from Philippine mobile operator data. Local lenders, financing companies, and microfinance institutions use it to underwrite applicants who would be declined for lack of information.
The constraint is obvious in the name. A lender operating beyond the Philippines will need a second provider for every other market, which raises the total cost and complexity of a multi-country scoring programme.
Standout capability: telco scoring calibrated specifically for Philippine borrower behaviour.
Scores users based on a mix of device data, behavioural signals, and psychometric questionnaires.
Best for: lenders understanding psychometric assessment for SME or first-time borrower segments.
Lenddo EFL established this category very well. The integrated business offers psychometric credit assessment, which asks applicants a structured set of questions and scores the response patterns, with device and behavioral analysis. Psychometric testing has found specific use in SME lending; this is where a business owner’s decision-making style carries information that financial statements do not capture.
Buyers should confirm current status directly before planning around this provider. Public product information and market communication have been updated less consistently than peer vendors in recent years, so support coverage, active markets, and roadmap commitments are worth verifying at the outset of any procurement conversation.
Standout capability: psychometric assessment for applicants with no data trail of any kind.
Assesses borrowers in Latin American markets using mobile-derived signals, including social media. Income indicators and residential data.
Best for: Lenders operating in the specific Latin American countries where Findo offers coverage.
Findo provides many types of signals through mobile phone use. These include social presence, income indicators, and location data. It converts them into a risk view for consumer lenders. Regional understanding is real, and the multi-signal approach captures the whole picture rather than a single-source score.
Availability is the constraint. Coverage extends to a limited set of Latin American countries, so regional expansion outside that footprint means finding another provider. Documentation and public technical detail are also thinner than higher-ranked entries, which lengthens the evaluation stage.
Standout capability: multi-signal mobile scoring calibrated for specific Latin American markets.
Selection is trimmed down to four practical questions: which applicants the lender cannot currently score, which data sources are legally and technically reachable, how the score will join the decision flow, and how quickly the model can be validated against actual results.
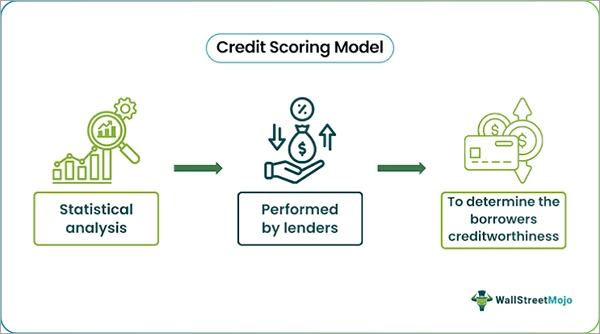
Alternative credit scoring services supply risk signals from sources beyond the traditional credit bureau file. That signal can take several shapes. Device metadata defines how a user organises and uses a smartphone. Telco data describes payment regularity and account tenure with a mobile operator.
Digital footprint data describes online account presence. Psychometric assessment describes decision-making patterns through structured questions. Machine learning applied to internal records extracts more predictive power from data the lender already holds.
Each source answers a slightly different question, which is why many risk teams run two providers rather than one.
These capabilities separate a score that changes lending outcomes from a data feed that sits unused in a warehouse.
Credolab provides a behavioral score during the application session itself, which actually helps the signal in front of the approval decision instead of after it.
RiskSeal delivers a digital footprint check through an API call early in the funnel, where a legitimacy signal filters synthetic identities before underwriting begins.
TrustingSocial achieves high match rates in Vietnam, Indonesia, the Philippines, and India through a direct mobile operator approach.
FinScore concentrates entirely on Philippine subscriber data, and Findo covers a limited group of Latin American countries, so both suit single-market lenders rather than regional programmes.
Credolab curates scorecards from the lender’s own historical performance files, so the model reflects the portfolio it will govern.
Zest AI follows a similar path inside the lender’s existing application and loan records, rebuilding the scorecard through machine learning without adding an external data feed.
Credolab collects metadata only, with no contacts, messages, photos, or identifiers gathered from the handset, which lightens the legal review that usually delays alternative data projects.
Zest AI offers no new customer-facing collection step at all; it just works within records the institution already owns.
Zest AI generates adverse action reasoning and fair lending artefacts crafted for US supervisory review, which addresses the documentation load that avoids machine learning adaptation in regulated institutions.
Motiv8AI applies behavioural psychology to device signals, and that interpretive layer needs closer scrutiny during model validation than a straightforward statistical relationship.
The selection process should match the provider’s data source and delivery model to the lender’s decision flow, market footprint, and data readiness. Knowing invalid traffic in programmatic campaigns makes your understanding clearer.
A score earns its cost at the moment when it can shift an outcome. Behavioral signals from Credolab come during the application itself. It suits the origination decision, while RiskSeal fits the fraud screening stage that runs before underwriting.
Lenddo EFL introduces a questionnaire that works better in assisted or branch origination than in a fast digital journey.
FinScore and Findo provide strong local calibration within their own markets and nothing new with them. A multi-country lender requires a separate relationship for every additional territory.
Device-based scoring travels with the applicant’s handset rather than a national data source, which usually makes it the more practical base layer for a regional programme.
Providers that read social accounts, contact lists, or personal identifiers trigger longer legal review and stricter consent requirements.
Credolab works from metadata alone, so procurement usually clears data protection review more quickly, though the consent screen still demands wording that applicants will accept.
Credolab and Zest AI need historical outcome files before model development begins. This way, data preparation belongs in the timeline from the initial meeting.
Pre-built scores from TrustingSocial or RiskSeal can be tested against the same sample without a model build, which shortens the pilot while offering less calibration to the specific book.
Each vendor in this category publishes tough performance figures, and many of them are measured on populations a bureau already defines properly.
The number that decides the business case is lift on the declined and marginal segment, measured on the lender’s own applications.
These services fit lenders that need to score applicants the bureau file describes poorly, or that need stronger model performance from data already in hand.
Credolab fits this group because device metadata is generated at no marginal acquisition cost while a journey the lender already took control of.
Motiv8AI collects through a similar SDK pattern, with an added behavioural read that supports collections design as well as approval decisions.
TrustingSocial approaches borrowers through operator records in Southeast Asian markets where formal credit files are hard to get.
FinScore serves the same purpose inside the Philippines, where a large share of adults hold no bureau record of any kind.
Zest AI addresses the fair lending documentation and model risk review that generally stall machine learning adoption in supervised institutions.
The approach works best where the lender holds several years of clean application and charge-off history.
RiskSeal provides a quick legitimacy check from online account presence before an application goes through underwriting.
Lenddo EFL remains relevant for SME and first-time borrowers who leave no digital trail at all.
Most failed alternative data projects share the same root causes: a signal with no decision attached, a coverage mismatch, or a validation exercise measured on the wrong population. Traditional vs. AI Digital marketing agency concepts work on a similar scale.
A score with no policy change behind it produces a dashboard rather than revenue.
Describe the acceptance regulations, the target segment, and the measurement window before the first integration call with Credolab, TrustingSocial, or any other provider.
FinScore and Findo perform better within their own countries and provide nothing outside them. That really turns a promising pilot into a dead end at expansion time.
Coverage should be confirmed market by market before scoring capability enters the conversation.
Device collection relies on a permission flow that applicants really accept, and poor wording depresses opt-in rates enough to weaken an otherwise sound model.
Credolab reduces the legal side of this problem through metadata-only collection, though the consumer-facing screen still needs care.
A test limited to booked loans measures performance on the population the lender already scores correctly.
The group that determines the business case is the declined file. It means reject inference or a historical sample including declines is owned by the test design.
Credolab operates without any bureau record, since the score comes from device and web metadata generated during the application itself. TrustingSocial serves the same gap in markets where its operator partnerships offer subscriber history.
Device metadata defines how a person organises and interacts with their own phone, captured during the application session. Telco data determines the relationship with a mobile operator over time, including recharge patterns and account tenure, and needs an operator agreement to access.
Credolab gathers metadata only, with no contacts, messages, photos, or identifiers gathered from the device. Zest AI works entirely within information the lender already holds, so it offers no new consumer-facing collection step.
RiskSeal needs only an API call, with no SDK embedded in a mobile app and no release cycle to plan around. SDK-based providers need a mobile release, and telco providers require operator agreements in place first.
Credolab and Zest AI both develop scorecards from client outcome files, which means the model reflects the particular portfolio it will govern. That process requires historical performance data supplied at the start.
Psychometric assessment from Lenddo EFL remains relevant for SME and first-time borrowers without any digital or financial trail. The questionnaire adds friction to a fast digital journey, and regulatory scrutiny of inferred traits has jumped in several markets.
Providers tied to a single market, including FinScore and Findo, need a separate relationship for every additional country. Device-based scoring travels with the applicant’s handset, which generally makes it the more practical base layer for a multi-country programme.
Several programmes run a retrospective test against historical applications before any live deployment, followed by a champion-challenger period in production. Data protection review often sets the pace, and providers that collect no personal information generally clear that step faster.
In most regulated markets, they sit alongside the bureau score instead of replacing it, adding lift on the segment the bureau describes poorly. Full replacement usually happens only in markets where bureau coverage is minimal.
Buying a score before defining the policy change it will drive. The toughest programmes specify the target segment, the acceptance rule, and the measurement window before the first integration call.